When we published our first overview of global ocean energy progress, the sector was still dominated by pilot projects and laboratory demonstrations. Several years later, the picture has changed materially. Tidal-stream farms are producing electricity at scale in European waters, multiple full-scale wave devices reached the sea in 2024, and policymakers have begun to treat ocean energy as part of the offshore renewables toolbox rather than a distant research topic. For Wave for Energy, tracking that evolution matters because it shapes where ISWEC and related technologies can deliver value first: island grids, offshore assets, and coastal communities that need predictable renewable power.
From prototypes to pre-commercial pipelines
Europe remains the global leader in emerging ocean energy technologies. According to Ocean Energy Europe’s Stats & Trends 2024 report, the continent added about 1.23 MW of new ocean energy capacity in 2024, including tidal-stream machines and full-scale wave devices deployed in five countries. Cumulative electricity production from European demonstration projects and tidal farms exceeded 106 GWh in 2024, evidence that devices are surviving multi-year operation and improving availability.
Policy support is increasingly tied to revenue certainty rather than grants alone. Ring-fenced Contracts for Difference in the United Kingdom and feed-in mechanisms in France have helped developers move toward financial close on pre-commercial tidal farms. Ocean Energy Europe reports a publicly supported deployment pipeline of roughly 165 MW across 15 farms scheduled within the next five years—still modest compared with offshore wind, but an order of magnitude larger than the sector’s installed base a decade ago.
What the EU data show today
The European Commission notes that Europe added around 1,230 kW of ocean energy capacity in 2024, with sustained public and private investment in research and pilot projects over the preceding decade. The EU Blue Economy Report 2025 (DG MARE) puts emerging operational ocean energy capacity in the EU at 2.82 MW at the end of 2024, including about 1.12 MW of wave energy and 1.63 MW of tidal-stream capacity, plus small salinity-gradient installations. Additions in 2024 (770 kW) were slightly above 2023 levels, showing gradual rather than explosive growth—consistent with a sector still climbing the learning curve.
Wave energy specifically remains behind tidal stream in megawatts installed, but 2024 saw continued deployment of full-scale wave converters. That matters for Mediterranean developers: wave resources are lower than in the North Atlantic, so technologies that perform in moderate seas—such as gyroscopic converters tested in Italian waters—are competing on energy capture per unit of steel, not on matching Atlantic storm conditions.
Wave energy in the Mediterranean context
Research on ISWEC and other Mediterranean concepts highlights both constraints and opportunities. Island territories without interconnections face high electricity costs and diesel dependence; wave power along Sicilian and Sardinian coasts can exceed 7–13 kW per metre of wave front in energetic zones, according to project-specific assessments used in Italian demonstration sites. Integrating wave with photovoltaic and storage—as done in hybrid plants offshore Ravenna and in island trials—can smooth variability and improve capacity factors for small grids.
Environmental integration remains central. Slack-moored floating devices that keep moving parts inside a sealed hull reduce biofouling and corrosion risks compared with hinged or paddle architectures. Monitoring programmes around Pantelleria and Ravenna have paired energy production with marine noise and habitat studies, reflecting EU expectations for offshore renewables in Natura 2000 and coastal parks.
Barriers that still slow commercial roll-out
Despite progress, ocean energy is not yet bankable at utility scale. Capital costs remain high, insurance and O&M procedures are still being standardised, and port infrastructure for launching multi-hundred-tonne devices is uneven across Member States. Grid connection timelines for remote islands can exceed hardware build schedules, as seen in early Pantelleria campaigns where resistive loads were used while permits for export cables were finalised.
International competition is intensifying. Ocean Energy Europe warns that strong state support in the United States and China could erode Europe’s technology lead unless deployment pipelines convert into serial manufacturing. For SMEs and spin-offs, that implies focusing on niches—oil & gas platform electrification, aquaculture, desalination coupled with wave power—where value per MWh is higher than on mainland wholesale markets.
Implications for Wave for Energy
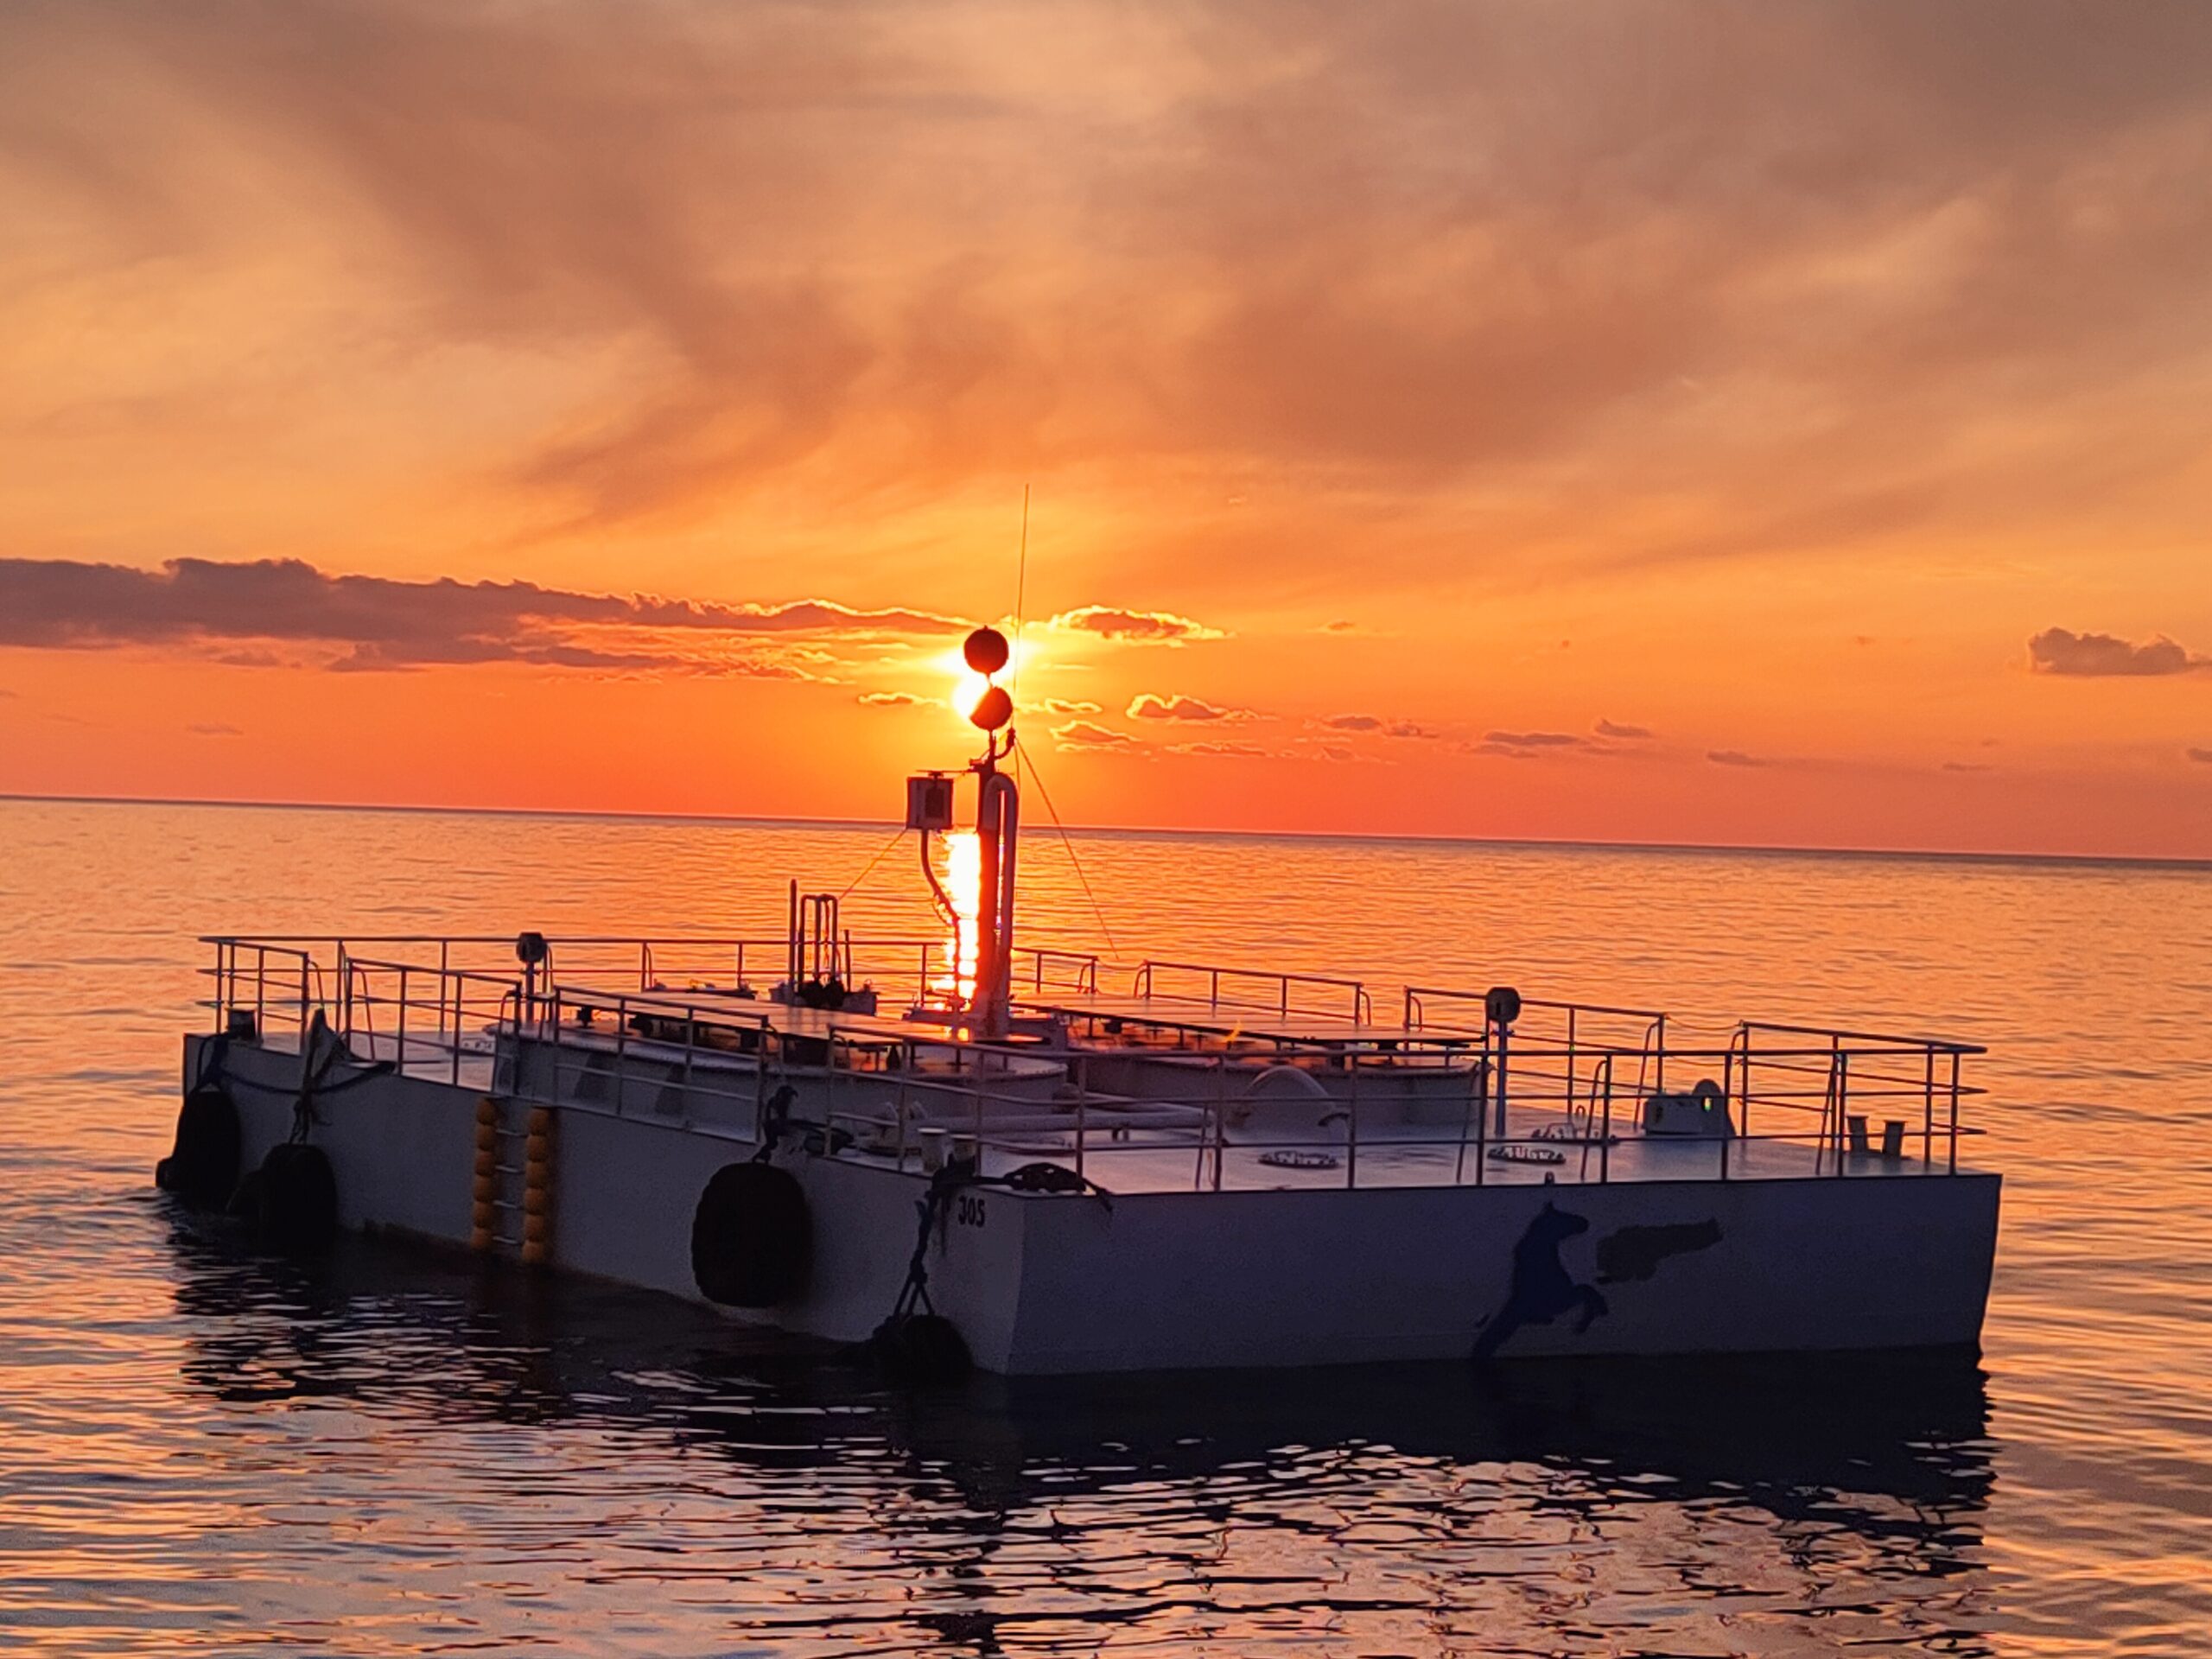
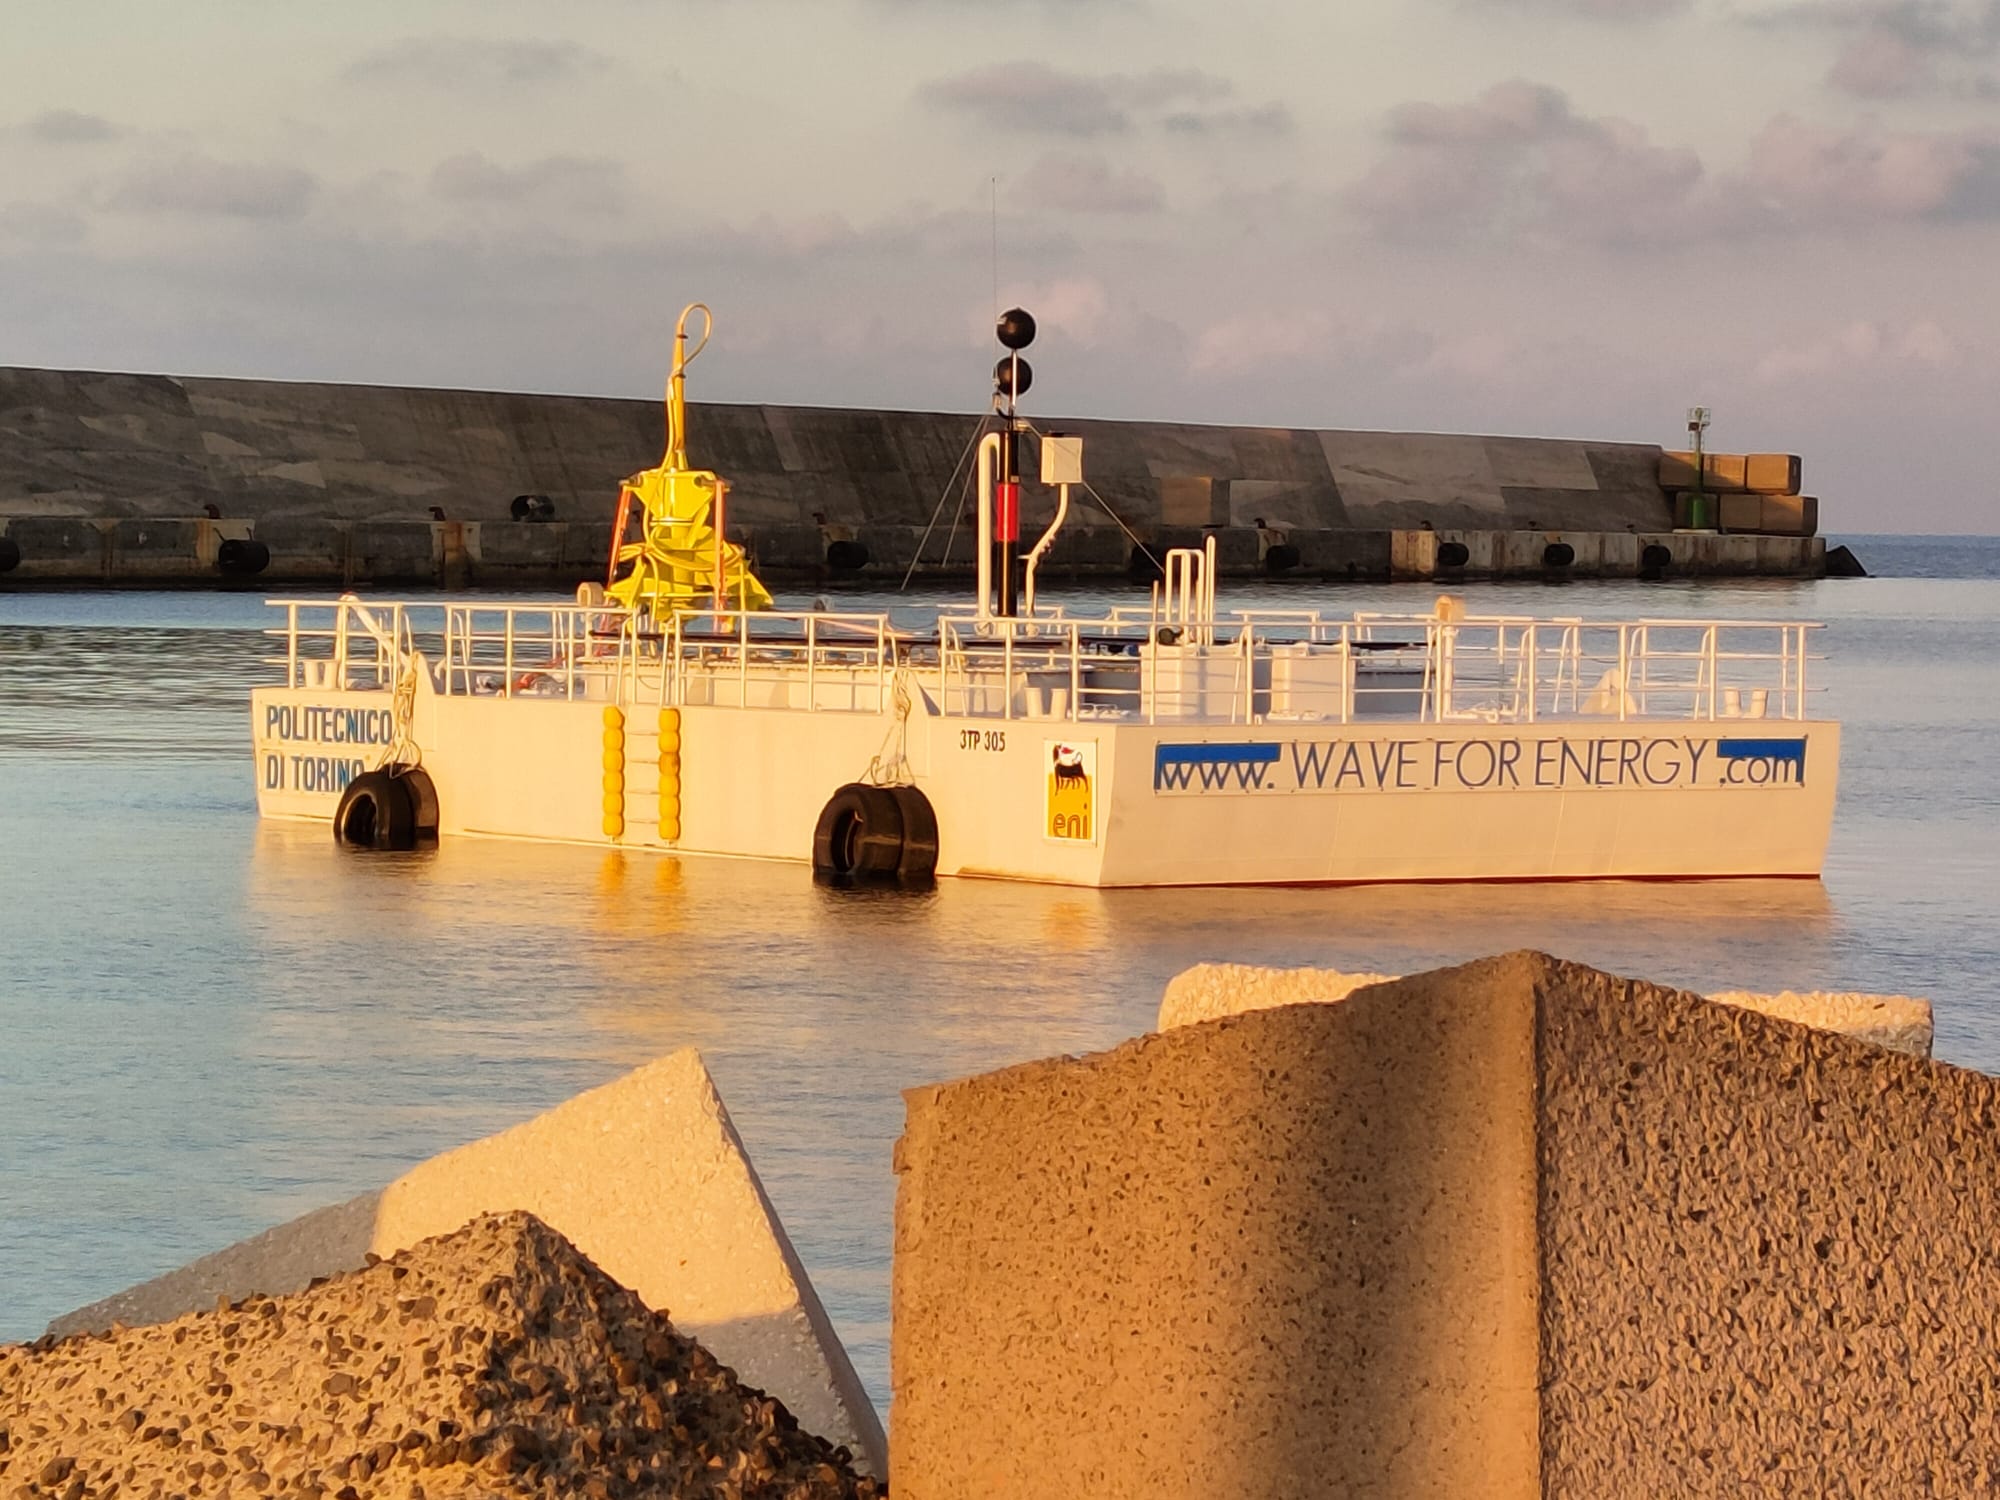
Our roadmap aligns with the sector’s realistic near-term role: prove reliability in real sea states, integrate with hybrid microgrids, and reduce levelised cost through design simplification and active control. Installations with Eni offshore Ravenna and grid-connected trials near Pantelleria are stepping stones toward second-generation machines with higher rated power and automated tuning using high-performance computing for site optimisation.
Ocean energy will not replace offshore wind this decade, but it can complement it where wave and wind resources overlap, sharing export cables and marine spatial planning. For policymakers, the task is to keep demonstration funding while introducing stable revenue mechanisms for the first commercial arrays. For technology providers, the task is to convert learning from each deployment into documented performance data—the currency investors now require.
Looking ahead
The next five years will show whether the 165 MW European pipeline materialises on schedule. Success would validate industrial supply chains for anchors, dynamic cables, and marine surveys; delay would signal that further cost reduction and risk sharing with utilities are still needed. Either outcome will inform how quickly island communities can treat wave power as more than an experimental line item.
We will continue to share results from our operating assets and R&D partnerships so that regulators, investors, and coastal stakeholders can judge ocean energy on measured performance rather than aspiration alone.
Sources
Ocean Energy Europe — Ocean Energy: Stats & Trends 2024 (April 2025). Type: industry statistics report.
European Commission — Offshore renewable energy (2024 overview). Type: official EU institution.
European Commission (DG MARE) — Marine renewable energy — EU Blue Economy Report 2025 (2025). Type: official EU publication.